With Tranche 2 of the Anti-Money Laundering and Counter-Terrorism Financing (AML/CTF) reforms in effect since 1 July 2026, the conversation has shifted from understanding the obligations to applying them in real matters. This session focused on the questions now coming through from conveyancers and property lawyers around customer due diligence (CDD) timing, source of funds, complex client structures, and everyday compliance processes.
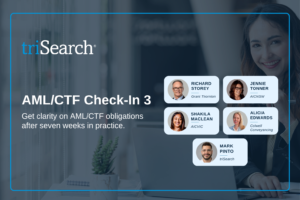
Mark Pinto, Major Account Manager at triSearch, was joined by Richard Storey, Partner, Risk Consulting at Grant Thornton; Jennie Tonner, President of the Australian Institute of Conveyancers NSW Division (AICNSW); Shakila Maclean, President of the Australian Institute of Conveyancers Victorian Division (AICVIC); and Alicia Edwards, General Manager of Operations at Colwell Conveyancing Group.
Jennie Tonner summed up how the conversation has changed: before 1 July, the question was “What do I have to do?”. Now, the questions coming through are far more specific.
Here’s a recap of some of the key topics discussed.
What’s new in the triSearch Compliance Centre?
The session opened with an update on improvements made to the triSearch AML/CTF Compliance Centre since 1 July. Recent changes include:
- Reusing previously completed verification of identity (VOI) for repeat clients
- Politically exposed person (PEP), sanctions, and adverse media monitoring
- Adding notes and supporting documents to transactions
- Refined company onboarding workflows
- In-person AML workflows for clients who cannot complete the process digitally
The team is also testing customisable client risk assessment questions, giving firms greater flexibility to include risk factors relevant to their own business alongside the standard assessment.
When should conveyancers complete customer due diligence?
Timing remains one of the most common questions.
For a sale: the panel discussed completing CDD early, once the vendor has instructed you to act and you’re preparing the contract. AUSTRAC treats the designated service as starting once a transaction exists, but completing CDD at instruction avoids a last-minute scramble when an offer is accepted.
For a purchase: there can be more flexibility. A prospective buyer may ask you to review several contracts before they purchase a property. The panel discussed the distinction between reviewing or advising a contract and progressing an actual transaction. In practice, CDD may occur once the buyer has entered the transaction,
Consider what service you are providing, when the transaction is progressing, and keep a clear record of the approach taken where the timing is less straightforward.
Source of funds: how far do you need to go?
Source of funds continued to be one of the biggest areas of discussion. The panel emphasised that conveyancers are not expected to conduct a forensic investigation into every matter. Further enquiries should be guided by risk, particularly where something about the client, transaction or explanation does not add up.
When do I need to look at source of funds or a source of wealth? Enhanced CDD mainly applies to high-risk clients or transactions, foreign PEPs, matters where an SMR has been lodged and you continue acting, or prescribed foreign countries. It is unlikely to apply to most standard matters. Your AML/CTF policies should clearly set out when enhanced CDD is required.
How far do I need to investigate? Only far enough to decide whether something is suspicious. You don’t need to find a definitive answer. Investigating further is a matter for AUSTRAC and law enforcement.
What should I look for in a bank statement? It depends on the client. A statement on its own may not tell you much, and a conversation often tells you more. Jennie gave an example: a first home buyer paying mostly in cash, using six bank accounts with repeated deposits just under $50,000. Combined with other high-risk factors, that was enough for her to submit an SMR without going further.
What if the client refuses to give information or documents? That refusal, combined with a lack of transparency, may give rise to suspicion. Record it in a file note and consider whether an SMR is required. If initial CDD cannot be completed, you cannot begin providing the designated service. Do not tell the client an SMR has been lodged or is being considered, as this may amount to tipping off.
How do you onboard trusts, SMSFs, and companies?
Companies, trusts and layered ownership structures remain a complex part of onboarding. The key is to identify who ultimately owns or controls the entity, including individuals with 25% or more ownership or control. The goal is to understand the structure well enough to identify the relevant people and assess the risk.
On a self-managed super fund (SMSF) purchase, do I onboard the bare trustee as well? Yes. The bare trustee will be the registered owner, so onboard the SMSF trustee, the bare trustee, and keep the document appointing the bare trustee.
Do vendor trustees get the same due diligence as purchaser trustees? Yes. Source of funds questions may differ, but you still need to work through any layered structure to identify the beneficial owners.
What’s the general rule for entities? Work out who actually controls the entity and the funds.
How do you verify a client acting under a power of attorney?
Power of attorney matters are another area where onboarding can become more nuanced. Where someone is acting under a power of attorney, firms need to verify the person acting under that authority and confirm that the authority itself is valid.
How do I handle a client acting through a power of attorney? Get VOI for the attorney, check the power of attorney is valid, and still identify and verify the principal, who remains your customer.
Is a medical certificate always needed? No. It is used when the principal has lost mental capacity and can’t complete VOI. Where the principal simply finds the process overwhelming, VOI on both is still possible. The panel expects to see this more often as clients age and move into retirement villages.
What does a compliant file look like?
Is there an end-to-end checklist AUSTRAC will sign off on? No adviser can guarantee what AUSTRAC will accept. The Compliance Centre workflow is built on AUSTRAC’s AML/CTF program starter kits and is designed to support the core CDD steps.
What else should I do? Keep your own settlement checklist as a second check, confirming the AML screening is complete and the risk result is recorded before settlement.
How long does ongoing customer due diligence last? For the length of the business relationship, which for most conveyancing matters ends at settlement. If a client is charged with fraud mid-matter, for example, you may need to reassess their risk.
What AML/CTF records should conveyancers keep?
One message ran through almost every topic: the file should clearly show what happened and why.
Someone reviewing the matter later should be able to understand what was checked, whether anything unusual arose, and how the firm reached its decision. Clear file notes, supporting documents, and recorded reasoning are therefore an important part of the process. AML/CTF compliance is not simply about ticking boxes but being able to demonstrate how the risk was assessed and managed. AUSTRAC requires CDD records to be kept for seven years after the business relationship ends.
How firms are managing the AML/CTF workload
The additional time and workload created by AML/CTF also featured strongly in the session. Jennie encouraged firms to factor this extra work into their pricing, while Alicia shared how her firm established a dedicated compliance team and refined its processes as volumes grew. Since July, Alicia’s firm has completed more than 2,500 AML verifications while reducing turnaround times, showing how firms are adapting their workflows as AML/CTF becomes part of everyday conveyancing.
Missed the session?
Watch the recording below to hear every question the panel covered.
Didn’t get your question answered, or need help with your triSearch Compliance Centre? Contact your Account Manager.
triSearch provides software solutions for conveyancing processes. Users remain responsible for compliance with applicable laws and regulations. This recap is general information only and isn’t legal advice.